What you'll learn
Key ideas from Principles
These ideas compress the book's argument without treating the author's view as settled fact. Use them as an orientation before reading the full work or listening in Wiseley.
Pain and failure become useful information when reflection identifies the weakness, condition, or root cause behind an unwanted result.
The five-step loop moves from goals to problems, diagnosis, design, execution, and renewed learning.
Radical open-mindedness separates learning from deciding and values truth, credible reasoning, and understanding over appearing right.
Principles turn recurring cases into recognizable types, compact rules, and revisable algorithms, though hybrid cases still require judgment.
A learning culture makes reality discussable through shared truth-telling, visible reasoning, and responsibility to raise important concerns.
Idea meritocracy hears every view while weighting authority by relevant experience, track record, and causal reasoning.
Problems become useful when managers detect them early, trace proximate failures to recurring human or design causes, and redesign accordingly.
Tools and protocols turn principles from stated beliefs into repeatable, inspectable behavior.
Inside Principles
Read the first chapter in full here. The other 7 continue in the Wiseley app.
Chapter 1 of 8 · 8 min · Audio & text
From Failure to Principles
Principles, by Ray Dalio.
Ray Dalio presents principles as the residue of a life in which ambition repeatedly collided with reality. He says his success came less from knowing than from knowing how to deal with what he did not know. Principles became his way to identify what was true, decide what to do, and recognize recurring situations. They were not polished doctrines at first. They grew from ambitious goals, repeated mistakes, painful failures, reflection, and efforts to avoid repeating errors. Writing them down made their logic visible, allowed behavior to be assessed against them, and made revision possible.
Dalio describes himself as an ordinary, poor student whose weak rote memory and dislike of instructions pushed him to figure things out independently. His first stock investment tripled, but Northeast Airlines was acquired near bankruptcy; the result reflected luck more than sound reasoning. The early boom made markets seem easy. After the nineteen sixty-six peak, much of his market understanding was disproved. A favorable outcome, he learned, cannot certify the reasoning behind it.
As he kept buying falling stocks, he learned that prices reflect expectations, not just current conditions. Recent experience encourages people to project the present forward. The dollar’s break with gold and his study of earlier devaluations suggested that surprises can follow recurring causes, though patterns are difficult to identify in real time. The Nifty Fifty episode showed why a widely accepted sure bet may already be priced in. A limit-down pork-belly position added a harsher lesson: if a market cannot be exited, losses may be undefined. Trading requires aggression to earn returns and defense to remain in the game.
After being fired from Shearson for reckless behavior, Dalio started Bridgewater in nineteen seventy-five with support from brokers and clients. The small apartment operation turned market curiosity into models. He mapped agricultural systems through livestock, crops, weather, inventories, processing, and demand, moving from handwritten charts to spreadsheets. Modeling markets as machines, identifying causes, and writing decision rules became standard practice. Yet one supposedly certain bet cost about one hundred thousand dollars, most of his net worth, and hurt clients. Hidden risks could damage apparently safe positions, so experience had to produce humility and controls, not certainty.
The decisive correction came in the early nineteen eighties. Dalio studied debt crises, saw inflation and policy converging toward a severe break, and publicly predicted a depression as bad as or worse than the nineteen thirties. He held positions meant to protect against inflation and deflation, but the economy recovered and his forecast failed. He later explained the recovery through capital flows, Federal Reserve liquidity, and debt restructuring. Still, the immediate lesson was personal: he had been confidently wrong. Bridgewater nearly collapsed. He lost most of what he had built, dismissed employees, became its sole employee, lost Paul Colman, and borrowed four thousand dollars from his father.
The crash did not end his ambition; it changed its terms. Dalio attributed the failure to overconfidence, emotion, and neglect of historical precedent. He also saw that being directionally right does not solve timing. The central question became, “How do I know I’m right?” He sought independent thinkers who could expose omissions and developed four linked responses: seek smart dissent, know when not to hold an opinion, build principles that survive changing conditions, and balance risks so a wrong view does not end the game. Diversification became the practical expression of that humility. Carefully designed, uncorrelated bets could preserve upside while reducing catastrophic downside, though Dalio presented this as difficult and vulnerable to hidden flaws.
Rebuilding Bridgewater extended the same logic into systems. Colleagues recorded trade criteria, translated them into formulas, back-tested them across long histories, and compared computer outputs with human judgment. Computers processed more information without emotion; people contributed imagination, context, and interpretation. Disagreement often exposed something one side had missed, while exceptional events could still require human intervention. The aim shifted from predicting the future perfectly to responding better to information as it arrived.
Growth then made personal judgment and effort insufficient. By two thousand eight, innovation and expansion had left Bridgewater difficult to manage. Dalio worked about eighty hours across investing and management, while a study suggested his desired standard required one hundred sixty-five. He could not preserve quality by working harder. A Management Committee began probing his judgment and sharing oversight, with Dalio reporting to it. The need for shared principles was now organizational, not merely personal: learning and responsibility had to be distributed beyond the founder.
In twenty ten, after thirty-five years of leadership, Dalio planned to leave the CEO role, mentor replacements, and reduce dependence on him. The transition was expected to take several years because it contained more unknowns than knowns. It exposed another limit: investment performance remained strong, but leaders struggled with the founder’s departure. Dalio temporarily returned to the co-CEO role, and structural changes followed. He treated the episode as a painful learning experience. A durable organization needed capable leaders and checks and balances that could preserve its standards while replacing leaders who were no longer effective.
Looking back, Dalio says apparently unique crises began to resemble recurring categories. Reality became a chain of causes and effects, and principles became mental maps for recognizing patterns and choosing responses. They are not commands for everyone. He presents them as lessons shaped by his nature, goals, and consequences, which others should evaluate and adapt. His trajectory explains why the book needs them: ambition supplied pressure, failure supplied evidence, humility corrected confidence, risk control preserved the chance to continue, and systems carried learning beyond one person. Principles earned authority by surviving reality and keeping the next decision open.
Chapter 2 of 8 · 7 min · Audio & textIn the app
Reality, Pain, and Progress
Dalio’s framework begins with an uncomfortable premise: reality does not adjust itself to fit desire. Progress starts when a person accepts what is true, including limits, causes, and consequences, then acts on that understanding.
Chapter 3 of 8 · 9 min · Audio & textIn the app
Open Minds, Different Minds
Better judgment begins with admitting that any one person sees only part of reality. Dalio identifies ego and blind spots as the two main barriers to objective self-assessment, learning, and effective decisions.
Chapter 4 of 8 · 7 min · Audio & textIn the app
Decision Architecture Under Uncertainty
Good decisions begin before the decision itself. Dalio treats decision making as two distinct tasks.
Chapter 5 of 8 · 7 min · Audio & textIn the app
Culture Built on Truth
For Dalio, principles become meaningful when they shape the social environment where work is done. A learning organization cannot depend on private insight alone.
Chapter 6 of 8 · 6 min · Audio & textIn the app
Meritocracy and the Right People
Once an organization permits disagreement, it needs a way to decide whose reasoning carries more weight and who owns the result. Dalio calls this an idea meritocracy: neither autocracy, where the boss settles everything, nor democracy, where every opinion counts equally.
Chapter 7 of 8 · 8 min · Audio & textIn the app
Run the Organization as a Machine
Management works best above the stream of tasks. Dalio describes an organization as a machine: interacting people, responsibilities, processes, and feedback that turn goals into results.
Chapter 8 of 8 · 6 min · Audio & textIn the app
Make Principles Operational
The book’s closing argument is that principles do not become durable merely because people agree with them. Under pressure, intellectual agreement often fails to guide behavior.
Chapter 1 of 8 · 8 min · Audio & text: From Failure to Principles
Wiseley supports reading and listening to summaries in the app.
Continue in WiseleyAbout Ray Dalio
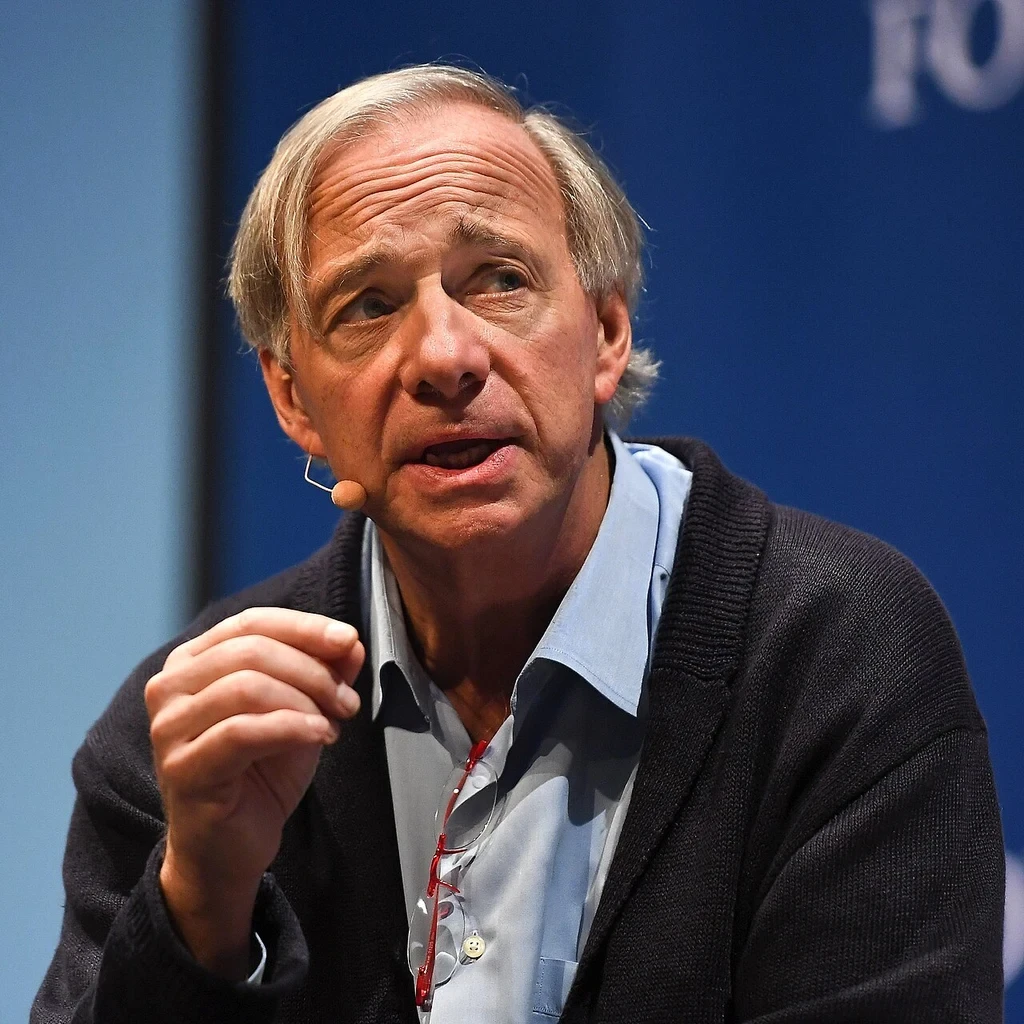
Ray Dalio is an American investor and hedge fund manager. “Principles” explores the principles the author developed for making decisions in life and business.
Explore more books by Ray Dalio