What you'll learn
Key ideas from Rich Dad Poor Dad
These ideas compress the book's argument without treating the author's view as settled fact. Use them as an orientation before reading the full work or listening in Wiseley.
The framework contrasts employment, security, and risk avoidance with ownership, investment, risk management, and financial self-reliance.
Financial literacy reads the direction of cash flow, distinguishing assets that add income from liabilities that consume it.
Minding your own business means building an owned asset column while keeping a profession when employment remains necessary.
Corporations separate business activity from personal finances, limit liability, and can support lawful tax planning.
Deal creators assemble overlooked value, capital, and capable people instead of only buying packaged products.
Long-term opportunity grows by combining technical ability with sales, marketing, communication, leadership, and financial intelligence.
Multiple viewpoints, learning associations, and practiced formulas widen financial understanding, while self-discipline determines whether knowledge becomes action.
Learning gains value when an unfamiliar financial idea is tested through concrete action and feedback.
Inside Rich Dad Poor Dad
Read the first chapter in full here. The other 13 continue in the Wiseley app.
Chapter 1 of 14 · 7 min · Audio & text
Two Fathers, Two Financial Futures
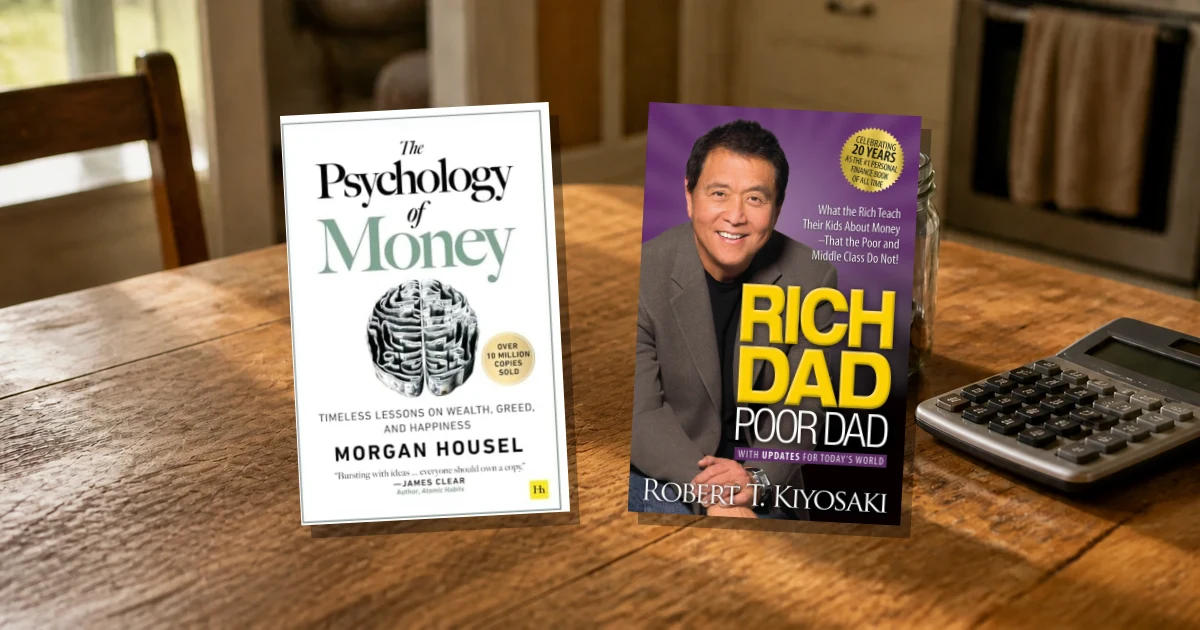
Rich Dad Poor Dad, by Robert T. Kiyosaki.
A familiar question sits behind Rich Dad Poor Dad: if someone receives a good education, works hard, and earns a solid income, why might that person still struggle financially? Robert T. Kiyosaki explores the question through two fathers who shaped his thinking. Both were strong, influential, hardworking men. Both began with money difficulties and family responsibilities. Yet their beliefs about money led them toward sharply different futures. One eventually became one of Hawaii’s richest men and left wealth to family, charities, and his church. The other left bills behind. In this story, rich dad and poor dad describe eventual financial paths, not the men’s starting positions.
One father represented conventional achievement. He valued degrees, professional credentials, advanced business education, and a good job. The other valued learning how money works and making money work for the learner. The contrast is not simply education versus ignorance. Both fathers valued education, worked hard, and earned significant incomes. The point is that academic success and earnings do not automatically produce financial security. A person can be qualified, respected, and well paid while remaining financially constrained. Financial education is presented as a separate kind of knowledge, affecting how people understand money and make decisions.
Conflicting advice became the narrator’s education. He had to compare two authorities rather than accept either one automatically. One father advised studying to find a good company to work for; the other advised studying to find a good company to buy. One emphasized safety and avoiding financial risk; the other emphasized learning to manage risk. Kiyosaki ultimately chose to learn about money from the less formally educated father. He presents that choice, echoed through the metaphor of The Road Not Taken, as a decision that shaped the rest of his life.
Money habits are also located outside the classroom. Money is taught mainly at home, while schools focus on academic and professional skills. Parents who lack financial knowledge may still give sincere advice—stay in school and study hard—yet leave their children with strong credentials and what the author calls a poor financial mindset. Kiyosaki extends this criticism to public finance, suggesting that highly educated officials can make money decisions without adequate financial training. He also raises concerns about future dependence on families or government if major support programs cannot meet their obligations. These are presented as concerns and hypotheticals, not established outcomes.
The two fathers use different questions. When the poor father says something cannot be afforded, the inquiry ends. The rich father asks how it could be afforded. That question is not a command to buy every desired thing. Its purpose is to keep the mind working, search for possibilities, and build the habit of financial problem-solving. The narrator compares this mental exercise with physical exercise. In the rich father’s model, repeatedly examining financial problems strengthens the capacity to find ways of making money. This is presented as a claim about practice and possibility, not independent proof that a particular strategy will make anyone wealthy.
The contrasts multiply. One father says love of money is the root of evil; the other says lack of money is the root. One sees children as a reason he cannot become rich; the other sees them as a reason he must become rich. One prefers that money and business stay away from the dinner table; the other treats them as subjects worth discussing. One sees a home as the family’s largest investment and greatest asset; the other calls a house a liability and warns that relying on it as the largest investment can signal financial trouble. One pays bills first, though both fathers pay on time; the other pays bills last while focusing on building investments. These examples set employment and ownership against each other: prepare an impressive résumé for a job, or prepare business and financial plans intended to create jobs. They also contrast saving small amounts with creating investments, and viewing taxes as redistribution from the rich with treating them as punishment for producers.
Security and self-reliance form another divide. One father values employers or government providing raises, retirement benefits, medical coverage, leave, vacation, tenure, and lifelong job protection. The other argues for total financial self-reliance and views entitlement thinking as a path toward financial need. His position is not that risk disappears, but that competence in managing it matters. The same attitude appears in their language about identity. Kiyosaki says the poor father repeatedly predicted that he would never be rich, while the rich father continued to think of himself as rich even after becoming broke. Being broke was temporary in that framework; poverty was treated as enduring.
Financial education is presented as a more durable source of power than money itself. Money is one form of power, while understanding how money works can help a person gain control over it. Positive thinking alone is not enough in this account; it must be joined to financial knowledge. The rich father taught these ideas over thirty years, stopping when he believed the lessons had finally been understood. Six guideposts recur: the rich do not work for money, financial literacy, minding one’s own business, taxes and the power of corporations, inventing money, and working to learn rather than working for money. These guideposts give readers and their children a starting point for navigating change and uncertainty, not complete answers. The two fathers leave the narrator with a lasting question: is financial success best measured by credentials and income, or by understanding how money works?
Chapter 2 of 14 · 5 min · Audio & textIn the app
Fear, Desire, and the Paycheck Cycle
A child’s desire to be rich begins with comparison. The narrator and Mike attend school with wealthier children.
Chapter 3 of 14 · 6 min · Audio & textIn the app
Making Money Work for You
Rich dad’s next move is to examine what happens inside a person under financial pressure. He says the first step is to admit actual feelings about money.
Chapter 4 of 14 · 6 min · Audio & textIn the app
Reading the Story of Cash Flow
Financial literacy begins with a simple question: when money moves, where does it go? Robert T.
Chapter 5 of 14 · 6 min · Audio & textIn the app
Build the Asset Column
A distinction that sounds simple changes the whole financial picture: a profession is not necessarily a business. A profession is the work that brings in a paycheck.
Chapter 6 of 14 · 7 min · Audio & textIn the app
Taxes, Corporations, and Financial Power
Taxes begin with a Robin Hood story: take from the rich and give to the poor. Kiyosaki says this made taxes politically attractive because poorer voters were told the levy would punish wealthy people.
Chapter 7 of 14 · 6 min · Audio & textIn the app
Financial Intelligence Creates Options
When conditions change, financial intelligence creates options. Robert T. Kiyosaki contrasts academic intelligence with what financial life often demands after formal schooling: courage, confidence, useful information, and adaptive thinking. A person may be highly educated and still feel trapped by one paycheck or familiar solution. In his view, intelligence matters when it helps someone recognize possibilities and act under uncertainty, not merely repeat what worked before. He uses Alexander Graham Bell to…
Chapter 8 of 14 · 5 min · Audio & textIn the app
Inventing Deals and Managing Risk
The contrast is between saving for security and investing to create or acquire assets. The author acknowledges that saving a fixed amount each month is sound advice.
Chapter 9 of 14 · 7 min · Audio & textIn the app
Work to Learn Across Skills
A job can be a classroom as much as a source of income. Kiyosaki argues that people should choose work partly for the skills and perspective it develops, not only for pay, benefits, or security.
Chapter 10 of 14 · 4 min · Audio & textIn the app
Turning Fear into Financial Courage
Financial literacy is only part of the route to financial independence. A person may understand assets, liabilities, and basic money mathematics yet fail to build an asset column that produces meaningful cash flow.
Chapter 11 of 14 · 3 min · Audio & textIn the app
Habits, Desire, and Honest Ignorance
Sometimes laziness is not inactivity but busyness. People can fill their days with work, errands, and obligations so they never have to face a problem in their relationships, wealth, health, or another important area.
Chapter 12 of 14 · 8 min · Audio & textIn the app
Ten Practices for Financial Capability
Financial capability is presented as something that can be awakened rather than a fixed talent. The ten practices are personal and adaptable, not an immutable prescription.
Chapter 13 of 14 · 5 min · Audio & textIn the app
Turn Ideas into Action
Financial ideas remain abstract until they change what someone does. Responding to readers who see his principles as philosophies, the author insists that understanding and action belong together.
Chapter 14 of 14 · 6 min · Audio & textIn the app
From Earned Income to Freedom
The closing financial model begins with a practical problem: how can a family pay for children’s education and prepare for retirement when effort, saving, borrowing, taxes, and a paycheck still leave income tied to labor? The book’s answer is financial intelligence—learning how cash is produced and turning earnings into assets that can work for their owner.
Chapter 1 of 14 · 7 min · Audio & text: Two Fathers, Two Financial Futures
Wiseley supports reading and listening to summaries in the app.
Continue in WiseleyWhat Rich Dad Poor Dad is about
Robert T. Kiyosaki asks a central question: Rich Dad Poor Dad contrasts two approaches to money: trading time for wages and building financial understanding, assets, and ownership. It asks why education and higher earnings can coexist with financial insecurity, then maps cash flow, risk, skills, and the conversion of earned income into portfolio or passive income.
Kiyosaki contrasts two teaching figures to challenge conventional beliefs about work, assets, liabilities, and financial education. The contrast carries the argument, but a memorable distinction is not a complete accounting or investment framework.
A Wiseley reading lens: Separate the story from the financial decision
This reading lens was written by Wiseley editors to help you examine the book’s choices and evidence.
A Wiseley reading lens: when the book labels something an asset, write down exactly what the author means. Compare that use with the ordinary accounting meaning rather than silently treating the two as identical.
Then identify what a real decision would require that the story does not supply: costs, uncertainty, obligations, and the reader’s circumstances. This is a way to evaluate the book’s language, not an instruction to make a transaction.
Read it with these limits in mind
- The teaching narratives do not establish that a strategy will work for a reader.
- The book’s asset and liability language differs from formal accounting usage.
- General financial arguments are not individualized investment or tax advice.
Who it helps, and when to read the whole book
Rich Dad Poor Dad tends to be most useful to:
- Separate the story from the financial decision.
- Readers comparing this book’s argument with the linked reading guide.
Read the complete book when:
- You want to examine the examples and reasoning behind the summary.
- The author’s narrative choices or qualifications matter to your interpretation.
About Robert T. Kiyosaki
Robert T. Kiyosaki is an American finance author and investor. “Rich Dad Poor Dad” explores the author's views on financial education, assets, and building income.
Explore more books by Robert T. Kiyosaki