What you'll learn
Key ideas from The Intelligent Investor
These ideas compress the book's argument without treating the author's view as settled fact. Use them as an orientation before reading the full work or listening in Wiseley.
A stock is an ownership claim on a business, so price must be judged against underlying value rather than treated as value itself.
Investment requires analysis, safety of principal, and an adequate return; a margin of safety accepts that estimates can be wrong.
Predetermined rebalancing, rather than forecasting, restores the chosen target after market movements.
Broad index funds make diversified ownership low-maintenance, but fees and tax records remain part of the defensive design.
Enterprise is defined by research effort and analytical competence, not by appetite for above-average risk.
Mr. Market supplies optional prices whose usefulness depends on the investor’s independence, patience, and business-based judgment.
Owner earnings, cash flow, debt, dilution, and capital structure reveal what reported profit leaves for common shareholders.
Risk includes both the chance of error and the consequences of being wrong, especially permanent damage to capital.
Inside The Intelligent Investor
Read the first chapter in full here. The other 9 continue in the Wiseley app.
Chapter 1 of 10 · 6 min · Audio & text
The Investor’s Mental Model
The Intelligent Investor, by Benjamin Graham.
Begin with the asset itself. A stock is an ownership interest in an actual business, with value that exists apart from its quoted price. The quote is the amount the market asks for that claim. It can be sensible or foolish depending on what the business is worth and what you pay. This distinction sounds simple, but it changes the investor's whole posture. You are not merely watching numbers move. You are deciding whether the price offers a reasonable exchange for an underlying economic interest.
From that starting point, Graham defines intelligent investing as a businesslike discipline. It does not require exceptional intelligence, inside information, or unusual business insight. It requires a sound framework and emotional discipline. An investment operation must rest on thorough analysis, promise safety of principal, and offer an adequate return. Adequate matters: the goal is not an extraordinary payoff, but a return the investor can accept without relying on fantasy. Analysis cannot remove error. A margin of safety acknowledges that estimates may be wrong and seeks enough distance between price and value to reduce the damage when they are. The question is less, "Can I predict perfectly?" than, "Have I paid a price that leaves room for being imperfect?"
Price discipline follows. The future value of an investment depends on the price paid, so a higher entry price lowers prospective return. A strong company can be a poor investment when enthusiasm has already made it expensive. A less glamorous or neglected company can be attractive when the price is low enough relative to its worth. Graham therefore treats quantifying price and value as an indispensable habit. Almost every security can be cheap at one price and too expensive at another.
That is also why growth stories deserve restraint. It is difficult to know which industries will expand, which companies will capture the expansion, and whether profits will follow physical growth. Even a successful company may produce disappointing investment results if its future is already fully reflected in the price. Forecasts and expert confidence do not change this arithmetic. Growth is an attribute of a business; it is not, by itself, a guarantee of a profitable purchase.
Market psychology creates the recurring gap between price and value. The market swings between excessive optimism and unjustified pessimism. When prices rise, securities can become more expensive and less attractive even as the crowd feels safer. When prices fall, they can become cheaper even as fear intensifies. The intelligent investor's advantage begins with refusing to borrow the crowd's mood. Graham says the investor's chief problem may be the investor himself: enthusiasm can become recklessness, and fear can turn a temporary decline into a lasting mistake. Intelligence here is chiefly a character trait—patience, discipline, independence, willingness to learn, and emotional control.
These ideas make the investment–speculation distinction precise. Wall Street often calls everyone who buys or sells a security an investor. Graham objects that an investment operation has three conditions: analysis, safety of principal, and adequate return. An operation missing those conditions is speculative. That does not mean speculation is illegal, immoral, or always useless. It can provide capital to untested enterprises and transfer risk between buyers and sellers. But the risk is transferred, not erased.
Speculation becomes unintelligent when someone mistakes it for investment, takes it seriously without sufficient knowledge or skill, or commits money that cannot safely be lost. A hot issue bought for a quick rise is speculation, whatever label is attached to it. Borrowing against securities adds another hazard because a decline can demand more money precisely when the investor is losing. If a person wants to speculate, Graham's discipline is to label the activity honestly, keep it in a small and separate fund, and prevent a successful gamble from silently taking over the investment program or the investor's thinking.
Finally, Graham distinguishes two legitimate investment temperaments. The defensive investor wants safety and freedom from bother, so prefers a durable program that does not depend on continual cleverness. The enterprising investor is willing to devote substantial time and care to finding sound securities that are unusually attractive. Neither identity is a badge of intelligence. The enterprising investor faces a prior obligation: extra effort must not produce worse results than a simpler policy. The book allows that active opportunities may exist, but it rejects the assumption that effort, forecasts, or a little extra cleverness automatically earns a reward.
Put together, the mental model is modest but demanding. Treat ownership as ownership, relate every price to value, seek an adequate return rather than excitement, and build a margin of safety because error is unavoidable. Then govern the process with patience and self-command. No method promises quick wealth, and no stock is free of risk. But a businesslike framework can protect the investor from confusing optimism with evidence, activity with intelligence, or speculation with investment. Later choices about policy and implementation rest on this vocabulary. Without it, a rising price looks like proof, a popular story looks like analysis, and a gamble can masquerade as a plan.
Chapter 2 of 10 · 9 min · Audio & textIn the app
Policy Before Prediction
Once an investor accepts that forecasts are unreliable, the central question changes. The task is not to predict whether stocks or bonds will win next.
Chapter 3 of 10 · 7 min · Audio & textIn the app
A Defensive Portfolio That Fits
Once an investor has chosen a stock-and-bond policy, the defensive task is to make the stock side durable enough to live with. Graham gives common stocks a place because dividends and reinvested profits historically helped protect purchasing power and raise long-run returns.
Chapter 4 of 10 · 7 min · Audio & textIn the app
Enterprise Without Illusion
Building on the policy and implementation already chosen, this chapter asks what justifies doing more than a defensive investor. Graham's answer is narrower than “enterprising” suggests.
Chapter 5 of 10 · 6 min · Audio & textIn the app
Let the Market Serve You
Quotations become useful when they stop being treated as verdicts. The investor owns claims on businesses, yet listed securities also deliver a changing price every day.
Chapter 6 of 10 · 7 min · Audio & textIn the app
Funds, Fees, and Advice
Funds are vehicles, not verdicts. They can make diversified, professionally managed investing accessible, convenient, and affordable.
Chapter 7 of 10 · 8 min · Audio & textIn the app
Read the Business Beneath Numbers
Security analysis, in Graham’s sense, is not an attempt to turn uncertainty into a decimal. It is a disciplined inquiry into a company’s business, finances, strengths, risks, and possible earning power.
Chapter 8 of 10 · 8 min · Audio & textIn the app
Choose with Evidence, Not Glamour
Selection begins where analysis ends, but Graham does not reduce it to one magic statistic. A suitable stock needs a bundle of quality, financial strength, earnings stability, dividends, asset support, and a price that does not require perfection.
Chapter 9 of 10 · 7 min · Audio & textIn the app
When Stories Override Balance Sheets
The recurring danger in these cases is not a shortage of information. It is that a persuasive story—size, daring, novelty, growth, or a fashionable industry—overpowers the economics beneath it.
Chapter 10 of 10 · 7 min · Audio & textIn the app
Margin of Safety, Made Durable
At the end of the book, margin of safety gathers earlier lessons into one answer to uncertainty. It means buying a security for materially less than a careful estimate of value, leaving room for mistakes and bad luck.
Chapter 1 of 10 · 6 min · Audio & text: The Investor’s Mental Model
Wiseley supports reading and listening to summaries in the app.
Continue in WiseleyWhat The Intelligent Investor is about
How can an ordinary person invest without mistaking market excitement for knowledge? Graham’s framework separates investing from speculation, relates price to business value, and builds decisions around diversification, margin of safety, costs, and behavior. The summary follows those principles through portfolio policy, security analysis, and corporate case histories.
About Benjamin Graham
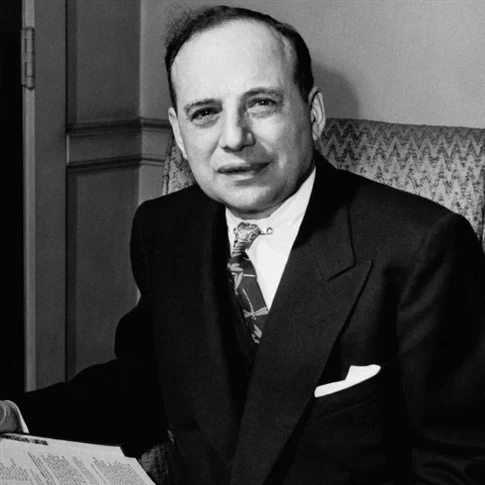
Benjamin Graham was an American financial analyst, investor, and professor. “The Intelligent Investor” explores the principles of value investing and the distinction between investment and speculation.
Explore more books by Benjamin Graham